Grief, Weaponized: The Criminals Who Mine Obituaries for Profit
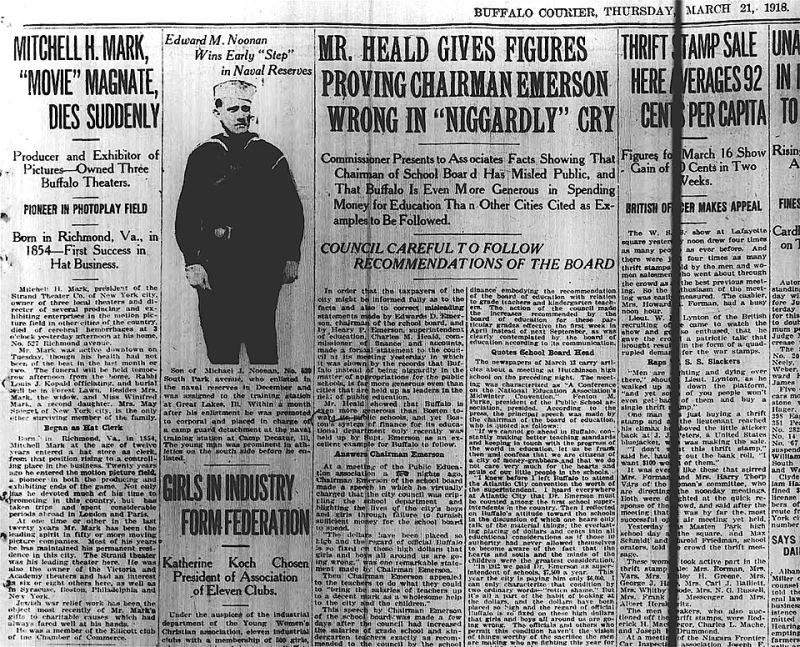
Photo: Buffalo Courier, Public domain, via Wikimedia Commons
The obituary is a public document by design. It announces a loss to the community, invites mourners, and celebrates a life. It also, in the wrong hands, functions as a dossier: full legal name, date of birth, hometown, surviving relatives, and often a maiden name — precisely the combination of details needed to unlock credit, accounts, and government benefits.
Fraud investigators and estate attorneys have watched a grim pattern solidify over the past decade. Within hours of a death notice appearing online, automated scrapers and human operators alike begin working the file. The practice has acquired an ugly shorthand in law-enforcement circles: ghosting fraud.
Why the Deceased Make Ideal Targets
The logic, from a criminal's perspective, is chillingly efficient. A deceased person will not notice fraudulent charges, will not receive collection calls, and will not dispute a credit inquiry. Credit bureaus do not automatically flag deaths; that responsibility falls to surviving family members or the estate's executor, and the notification process is neither automatic nor uniform.
The schemes tend to cluster into a few recognizable forms:
- Synthetic identity construction. A thief combines the deceased's real Social Security number with a new name and address, creating a hybrid identity that can pass credit checks for years.
- Tax refund fraud. Fraudulent returns filed in a decedent's name, claiming refunds before the IRS receives the estate's final filing.
- Account takeover. Using obituary details to answer security questions on existing bank, email, or brokerage accounts.
- Estate interception. Posing as a relative or creditor to redirect benefits, life insurance proceeds, or even funeral-related crowdfunding donations.
What Estate Attorneys Are Seeing
Practitioners in probate and elder law report that families routinely discover the fraud months later — often when a credit card statement arrives addressed to the deceased, or when the estate's tax preparer finds a refund already claimed. By then, unwinding the damage involves affidavits, credit bureau disputes, and in some cases IRS Form 14039, the identity theft affidavit.
The consensus among attorneys interviewed for this piece is blunt: prevention is dramatically cheaper than remediation, and the critical window is the first two weeks after death.
A Family's First-Fourteen-Days Checklist
No single step is sufficient, but together they close most of the doors:
- Request at least a dozen certified copies of the death certificate. Every institution will want an original.
- Notify the three major credit bureaus — Equifax, Experian, and TransUnion — and request a credit freeze and a 'deceased' alert on the file.
- Notify the Social Security Administration promptly; funeral directors often handle this, but confirm it was done.
- Contact banks, brokerages, and pension administrators in writing and flag the accounts.
- Limit the obituary itself. Skip the birthdate, birthplace, and mother's maiden name. A loving tribute does not require a data package.
- Secure the digital estate immediately: change or lock email accounts, close social media profiles or convert them to memorial status, and disable automatic payments.
- Monitor the mail. Redirected or missing statements are frequently the first visible symptom of takeover.
A Broader Policy Question
Advocates have long argued that the burden should not rest on grieving families. Proposals to make death reporting to credit bureaus automatic — triggered by the same records that inform the Social Security Administration — surface periodically in Congress and state legislatures, but none has achieved nationwide adoption.
Until that changes, the obituary will remain what it is today: a public announcement of loss that doubles, for a patient criminal, as a starting gun. Families who act in those first fourteen days deny the thieves their most valuable asset — time.